The Hidden Fundy Shore: Finding Your Home in Little Dyke and DebertEver feel like you’ve stumbled upon a secret that’s just too good to keep to yourself? That’s exactly how it

Dated: February 2 2026
Views: 354
 economy is neither overheating nor deteriorating rapidly. What This Means for Mortgage Rates When the Bank of Canada holds its key interest rate: Variable mortgage rates tend to remain relatively steady, since they’re tied to the prime rate. New fixed mortgage rates may not shift dramatically right away, but are influenced by broader market conditions, including bond yields and lender pricing. Buyers already locked into a fixed-rate mortgage won’t see their rate change until their term expires. Homeowners on variable-rate mortgages may continue with the same payment structure — for now. For many buyers and homeowners, this rate pause provides a degree of predictability — especially after years of rate increases and volatility. How This Could Impact Truro Homebuyers and Sellers For Buyers: If you’re thinking about buying, today’s steady interest rate environment can make it easier to plan your monthly payments and budget. While rates remain higher than the historic lows seen in previous years, the pause gives some buyers confidence to continue searching without fear of immediate rate spikes. For Sellers: Buyers’ borrowing costs are a key factor in housing demand. When rates are stable, buyers often feel more confident in making offers, and markets tend to move more predictably. For Refinancing or Renewals: If you have a mortgage that’s up for renewal soon, this rate outcome suggests lenders may not drastically change their offerings immediately — but it’s still important to compare rates from multiple lenders when refinancing. Looking Ahead: What’s Next? The Bank of Canada typically announces interest rate decisions about eight times per year, with the next scheduled announcement March 18, 2026. While this rate decision didn’t bring big changes, the Bank has emphasized the need to monitor inflation trends, growth prospects, and external economic pressures — and decisions later in the year could still surprise markets. Final Thoughts Rate decisions from the Bank of Canada may seem far removed from daily life, but they play a major role in the real estate market. Whether you’re buying your first home, selling your current property, or thinking about refinancing, understanding the interest rate environment helps you make smarter financial decisions. Thinking about how current interest rates affect your home goals in Truro or Nova Scotia? The Truro Home Team stays up-to-date with market conditions and can connect you with trusted mortgage professionals who’ll help you build a plan that works for you. Reach out anytime for local insight and guidance." width="600" height="400" />Bank of Canada Makes Latest Interest Rate Announcement (2026 Update)
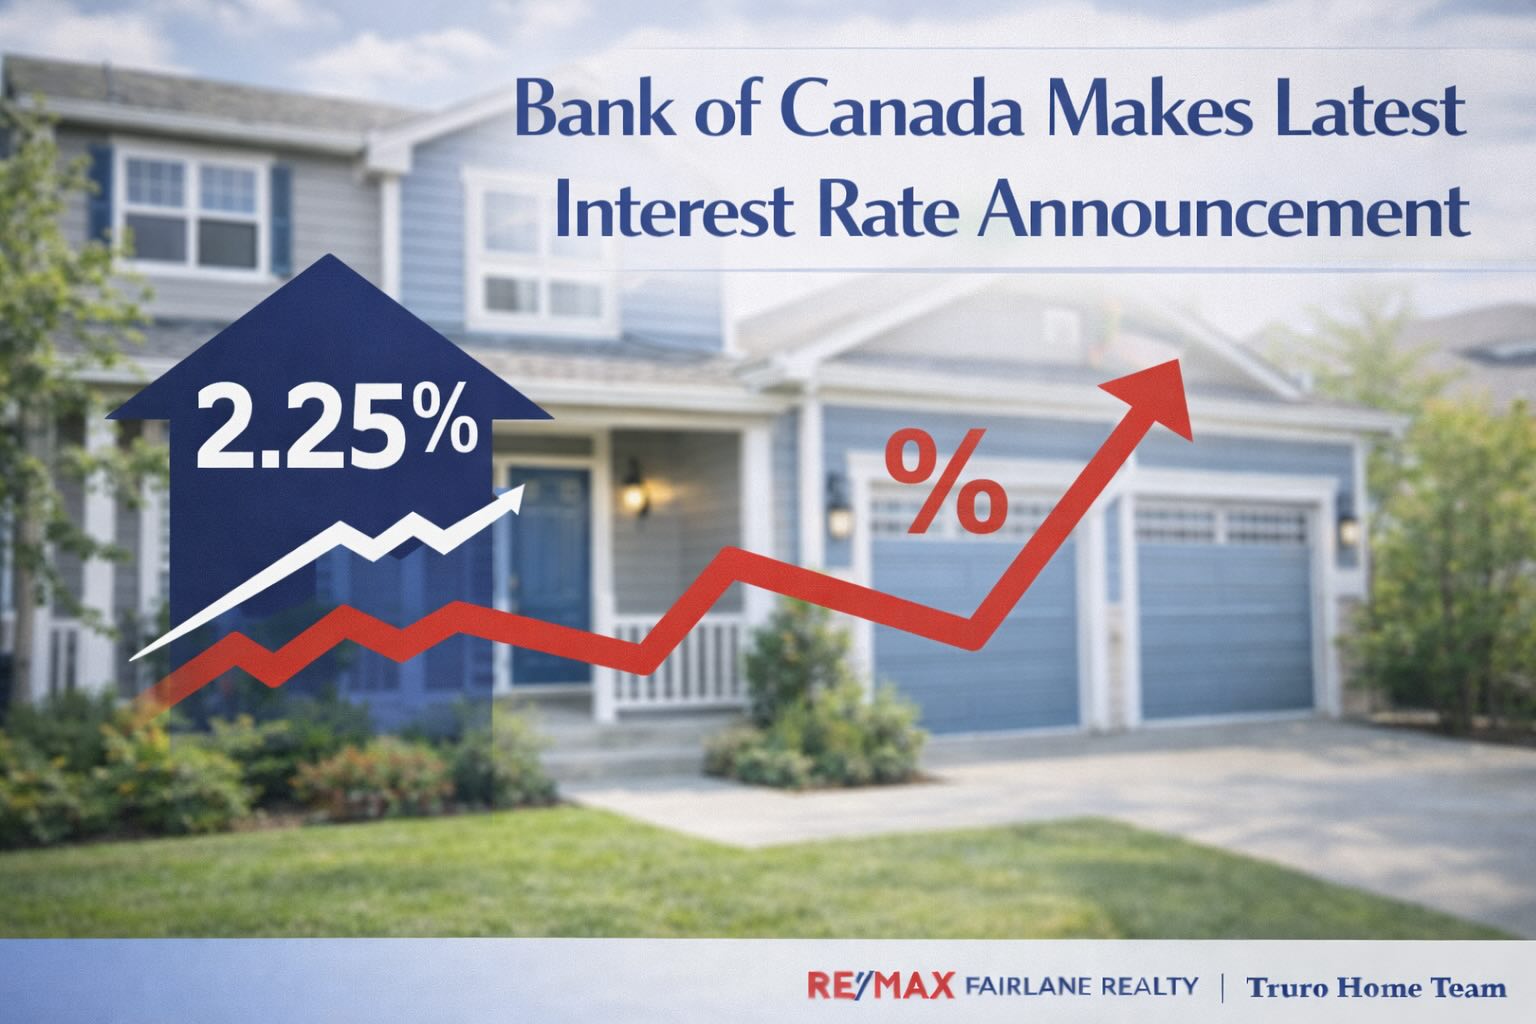
The Bank of Canada has just released its latest monetary policy decision, and it’s a development that affects anyone thinking about buying, selling, or refinancing a home. On January 28, 2026, the Bank held its key interest rate steady at 2.25 % — a move that economists and mortgage experts widely expected.
Understanding what this means, and how it could impact your real estate plans, is important for buyers and sellers in Truro, Colchester County, and across Nova Scotia.
In its most recent announcement, the Bank of Canada maintained its policy interest rate at 2.25 % and left the Bank Rate at 2.5 % and the deposit rate at 2.20 %.
The overnight rate is the benchmark used by financial institutions to set their own lending and borrowing rates — including the prime rate that influences variable mortgage rates and other loans.
According to the Bank’s statement, the decision to hold the rate reflects a cautious economic outlook. While inflation has remained relatively close to the Bank’s 2 % target, uncertainty around global trade, geopolitical tensions, and economic growth has made policymakers less confident about large near-term changes.
This means the Bank opted to keep rates unchanged rather than raise or cut them at this point — sending a message that the economy is neither overheating nor deteriorating rapidly.
When the Bank of Canada holds its key interest rate:
Variable mortgage rates tend to remain relatively steady, since they’re tied to the prime rate.
New fixed mortgage rates may not shift dramatically right away, but are influenced by broader market conditions, including bond yields and lender pricing.
Buyers already locked into a fixed-rate mortgage won’t see their rate change until their term expires.
Homeowners on variable-rate mortgages may continue with the same payment structure — for now.
For many buyers and homeowners, this rate pause provides a degree of predictability — especially after years of rate increases and volatility.
For Buyers:
If you’re thinking about buying, today’s steady interest rate environment can make it easier to plan your monthly payments and budget.
While rates remain higher than the historic lows seen in previous years, the pause gives some buyers confidence to continue searching without fear of immediate rate spikes.
For Sellers:
Buyers’ borrowing costs are a key factor in housing demand. When rates are stable, buyers often feel more confident in making offers, and markets tend to move more predictably.
For Refinancing or Renewals:
If you have a mortgage that’s up for renewal soon, this rate outcome suggests lenders may not drastically change their offerings immediately — but it’s still important to compare rates from multiple lenders when refinancing.
The Bank of Canada typically announces interest rate decisions about eight times per year, with the next scheduled announcement March 18, 2026.
While this rate decision didn’t bring big changes, the Bank has emphasized the need to monitor inflation trends, growth prospects, and external economic pressures — and decisions later in the year could still surprise markets.
Rate decisions from the Bank of Canada may seem far removed from daily life, but they play a major role in the real estate market. Whether you’re buying your first home, selling your current property, or thinking about refinancing, understanding the interest rate environment helps you make smarter financial decisions.
Thinking about how current interest rates affect your home goals in Truro or Nova Scotia?
The Truro Home Team stays up-to-date with market conditions and can connect you with trusted mortgage professionals who’ll help you build a plan that works for you. Reach out anytime for local insight and guidance.
I’m the Owner and Broker of REMAX® Fairlane Realty and lead the Truro Home Team, serving Truro and Colchester County. With over 18 years in the real estate industry, I bring strategic insight, stro....
The Hidden Fundy Shore: Finding Your Home in Little Dyke and DebertEver feel like you’ve stumbled upon a secret that’s just too good to keep to yourself? That’s exactly how it
Arisaig Adventures: Fossils, Wharfs, and Coastal Living at its BestIf you’ve ever wanted to feel like a time traveler without needing a fancy DeLorean, I’ve got the perfect spot for you.
Waterside Wonders: Living Near the Ferry and the Sea in CaribouHey there, neighbor! If you’ve ever found yourself daydreaming about a life where the rhythmic hum of a ferry and the gentle lap
Pugwash Real Estate: Your Quiet Coastal Retreat in the Village of FriendsIf you’ve ever dreamed of trading city noise for the sound of gentle waves and fresh salt air, pull up a chair and let
 Information should be deemed reliable but not guaranteed, all representations are approximate, and individual verification is recommended. Copyright ©2017 All rights reserved.
The trademarks REALTOR®, REALTORS® and the REALTOR® logo are controlled by The Canadian Real Estate Association (CREA) and identify real estate professionals who are members of CREA. The trademarks MLS®, Multiple Listing Service® and the associated logos are owned by CREA and identify the quality of services
provided by real estate professionals who are members of CREA. Used under license.
Show More...